All Categories
Featured
Building Financial Security with Whole Life Insurance
Table of Contents
The leading indexed universal life (IUL) insurance plans in 2026 come from carriers like Prudential, Pacific Life and Lincoln Financial, however the best option depends on your financial goals, danger tolerance and policy structure. This guide compares leading IUL service providers based on versatility, growth potential and policy features to assist you determine the greatest alternatives.
Pacific Life describes Pacific Life Insurance Coverage Company and its subsidiary Pacific Life & Annuity Company. Insurance coverage items can be issued in all states, other than New York, by Pacific Life Insurance Coverage Company and in all states by Pacific Life & Annuity Business. Product/material accessibility and functions may differ by state.

Pacific Life, its affiliates, their distributors and particular representatives do not provide tax, accounting or legal advice. Any taxpayer must consult based upon the taxpayer's specific circumstances from an independent tax advisor or attorney. Insurance items and their guarantees, consisting of optional advantages and any crediting rates, are backed by the monetary strength and claims-paying capability of the releasing insurance coverage business.
The home office for Pacific Life Insurance Business is situated in Omaha, Nebraska. Pacific Life Insurance Coverage Business and Pacific Life & Annuity Business.
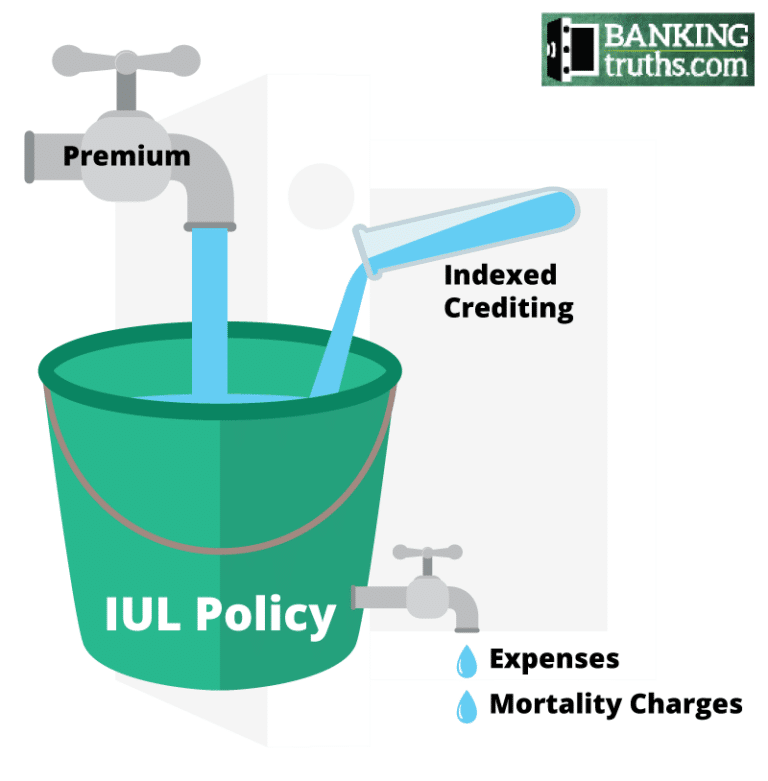
Updated September 2026 by, ChFC, CLU, AEP, EAThere is so much buzz and hate around Indexed Universal Life on social networks, you must be persistent about picking an IUL business before entering into a lifelong contract., IUL can be a vital tool to buffer against market losses and taxes in retirement while functioning as your own personal banking mechanism all along the way., Indexed Universal Life can be costly survivor benefit security cannibalizing your cash value account.
Comparing PPO and HMO Health Insurance Explained
In the sensible words of vocalist Tom Waits: Here's how you can become a better-educated shopper when vetting the very best Indexed Universal Life business: Do plan to max-fund your IUL for at least 4 out of the first 7-yearsDo run an illustration with lighter premiums in case you can't overfundDo run illustrations revealing both 1% and 2% below the default development rateDo ask to have a detailed fee report run for each situation to see the impactDo ensure the providing insurance coverage business is a mutual insurance companyDo learn how much of the money worth development comes from non-guaranteed bonusesDo demand a locked/capped policy loan that still participates in the indexed accountsDo demand strong S&P 500 indexed crediting accounts, preferably with an uncapped choice Don't be enchanted by algorithmic volatility-controlled indexes you can't track or understandDon't count on non-guaranteed bonuses to be there for you over the next several decadesDon't just select the illustration that appears to have the most money worth in retirementDon't choose your IUL company merely by who has the highest IUL cap rate (today)Do not simply compare IUL companies based exclusively on their default showed ratesDon't presume you will constantly be able to max-fund your IUL according to planDon't limp in and light-fund an IUL unless you can max-fund it very soonDon't pick a stock insurance provider over a shared companyBelieve us now, and thank us later.
Here are the four main aspects we concentrate on when evaluating the very best IUL policies for money build-up: Seeing the scores and balance sheets of the leading IUL business in a side-by-side contrast is the initial step in strolling our clients through the IUL education process. This is an item you're ideally purchasing into for your whole life, so the financial solvency and credit scores relative to other Indexed Universal Life insurance coverage business will be extremely essential.
If you do not see the name of what appears to be the best-performing IUL business on our list listed below, this is more than likely the reason that. The very best have not just one, but numerous diverse indexed accounts to grow your cash worth account in various market environments. Preferably, you have not just a high cap, however an uncapped technique as well.
Medicare in OrangeOptimal IUL Policies for Retirement
Be careful if an IUL's finest indexed accounts are volatility control indexes (VCIs). These VCIs are used by popular investment banks with complex algorithms to move you in and out of the marketplace. The problem is, you typically lose your direct exposure to stocks when you want it the many.

Latest Posts

Comparing HMO Vs PPO Health Insurance

IUL Policy Benefits for Future Security
Projecting Term Life Insurance Rates and Costs